
Rates Are Stuck Near 6.66%. Here Is What That Means If You Are Selling in/around Collin County This Fall
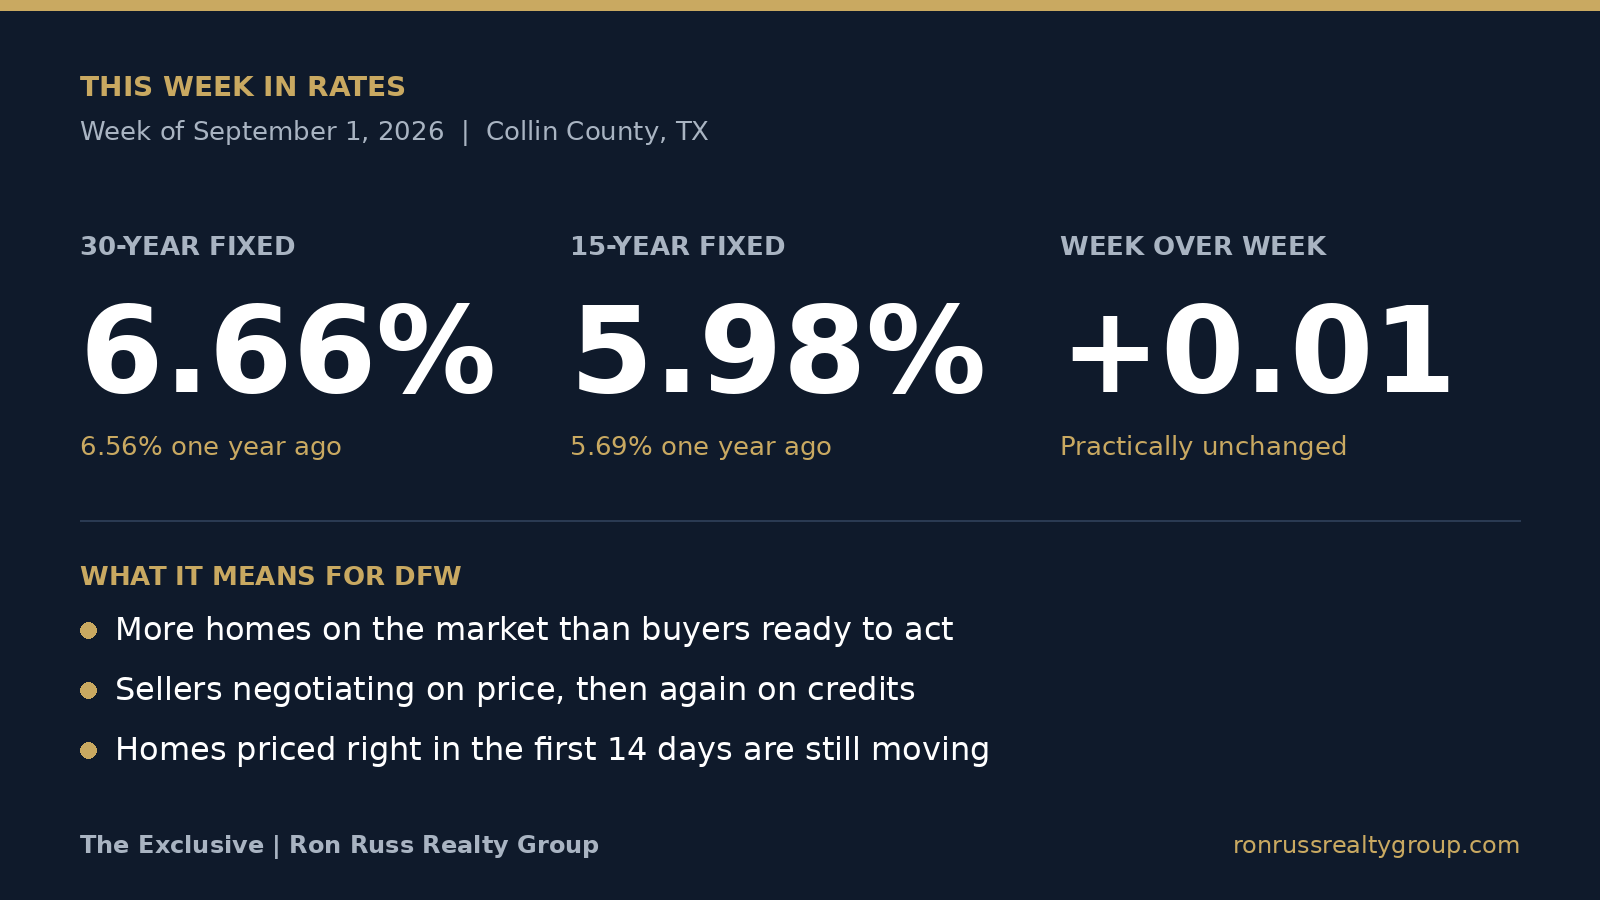
Every week I get a stack of rate updates from lenders, and every week the number barely moves. This week the 30 year fixed landed at 6.66%. A year ago it was 6.56%. The 15 year is at 5.98%, up from 5.69% last year. So if you have been waiting for rates to fall before you make a move, you have now been waiting about four years and the number is a tenth of a point higher than when you started.
I am not saying that to be negative. I am saying it because the plan has to be built around the market we have, not the one we keep hoping shows up.
Why rates are not budging
The new Fed Chair, Kevin Warsh, gave his first big speech at Jackson Hole on Friday and he was direct about it. He wants inflation back to 2 percent and he is not going to pretend we are close. The Fed's preferred inflation measure is still running well above that target. The Fed's main tool for closing that gap is keeping borrowing expensive, and mortgage rates follow.
There are a couple of things under the surface worth watching. July's core inflation reading came in softer than the headline suggests, oil has dropped into the low 80s, and the Treasury is talking about buying longer dated bonds, which is the part of the market that actually drives mortgage rates. Any of those could push rates lower. None of them are guaranteed, and the lenders I trust are not expecting anything in the 5s for a while.
So plan on 6.5% being normal. If it improves, great. If it does not, you are not stuck.
What is actually happening in our market
Nationally, the headlines say the market is shifting toward buyers, and around here I would agree. In Frisco, Prosper, Celina, McKinney and Allen, we have more homes on the market than we have buyers ready to act on them. That shows up in three ways I see every week:
-
Sellers are not getting full asking price. Homes are still selling, but the list price is the starting point of a negotiation, not the finish line.
-
Buyers are asking for credits before the inspection even happens. Seller credits used to be an inspection conversation. Now they are showing up in the initial contract, and then again after inspections.
-
Homes that are priced right still move. The ones sitting for 60 or 90 days are the ones priced for the market of two years ago.
Prices have not fallen off a cliff. Nationally, median prices have risen 37 months in a row, and DFW has been flat rather than down. But flat plus more inventory means the buyer has the leverage in most negotiations right now.
If you are selling in the next six months
Price it to sell in the first two weeks. In a market like this, your first 14 days are your best shot at a clean offer. A home that debuts too high and then chases the market down ends up netting less than the one priced correctly on day one, and it usually ends up giving credits on top of the reduction.
Expect to negotiate twice. Once on price, once on credits. Decide ahead of time what you are willing to give and where your floor is, so you are not making that call emotionally at 9pm with an offer on the table.
Get ahead of inspection items. If your roof, HVAC or water heater is going to show up on an inspection report, know that before you list. It is cheaper to fix or disclose than to credit.
If you are buying and selling at the same time
This is the best setup move-up buyers have had in years. Yes, you will give a little on the sale side. But you have leverage on the purchase side too, and at the mid to luxury price points that leverage is real money. A 2 percent credit on a $700,000 purchase covers a lot of the rate difference people keep waiting for.
The rate you are worried about is temporary. The house you buy is not. If you find the right home at the right price with a credit in your pocket, take it and refinance when the market gives you the chance.
What I am watching this week
Jobs data lands Friday. Bond prices are sitting right at a technical level where they either break higher, which would pull rates down, or fail and push rates to fresh 2026 highs. Between that and the September Fed meeting, the next two weeks could set the tone for the rest of the fall.
If you want to know what your home would sell for in this market, not last year's, let's chat and I will run the numbers with you. No pitch, just the data.
Sources
-
Nerd News Monday Market Update, MTG Nerd Group (Aug 31, 2026)
-
Guild Mortgage Weekly Mortgage Market Guide (Aug 28, 2026)
-
Realtor.com, "The Housing Market Is Moving in Favor of Buyers" (Aug 27, 2026)
-
NAR July 2026 existing home sales